How will Brexit affect the size of mortgage instalments?
Text from 2019. Laws, rates and prices may have changed since then. Ask an agent
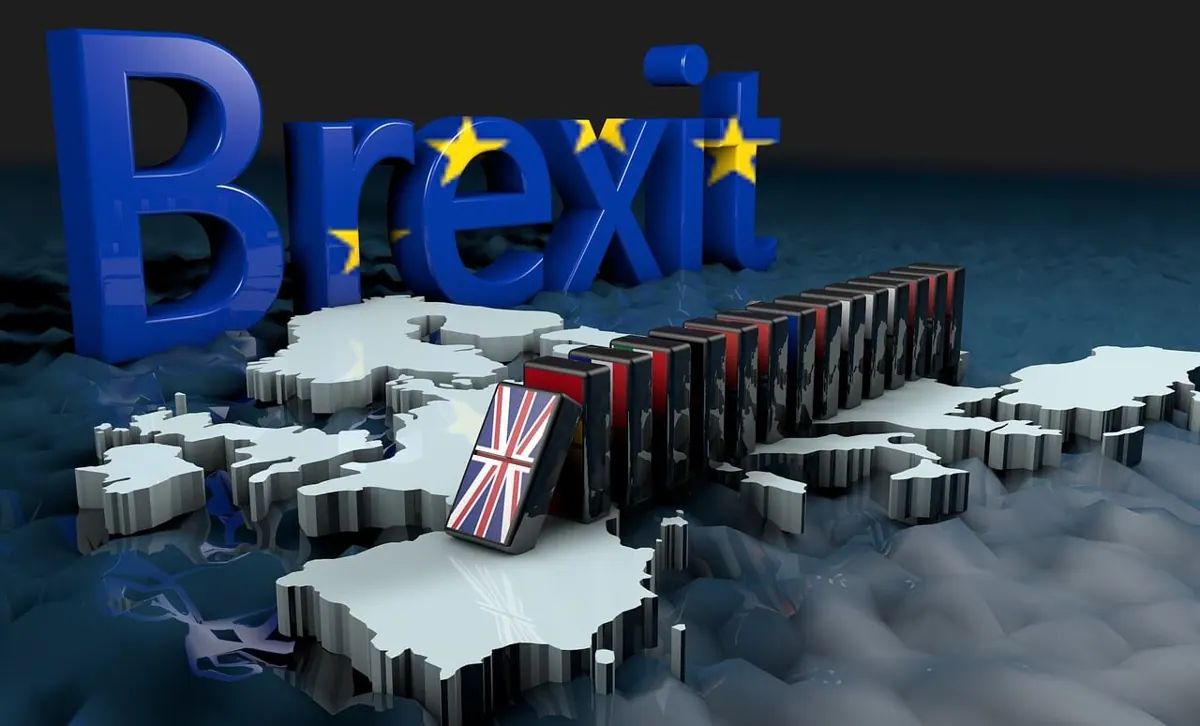
Discussions about the United Kingdom leaving the European Union focus mainly on international politics, the consequences for trade and the impact on the labour market. Meanwhile, Brexit may also be strongly felt by people investing in property.
Flight to Switzerland
When the results of the British referendum on leaving the European Union were announced, many investors reacted by "fleeing" towards the Swiss franc. Despite the considerable turbulence surrounding this currency, it still has a reputation for being fairly stable. Naturally, this had a strong effect on the size of the sums that were converted to protect capital. Inevitably, this had to show up immediately in exchange rates. And that could not remain neutral for holders of mortgages denominated in the Swiss currency.
Brexit and mortgages in francs
The franc rate, which had hovered around 4.01-4.05 PLN, fell to 3.94 on the night of 23 to 24 June. Briefly. In the morning, after the referendum results were announced, the jump was sharp, reaching 4.22. In the following days there was some stabilisation, and the CHF/PLN rate fell to 4.14 (data from Monday 27 June), but that is still a considerable difference.
For an instalment equivalent to 2,000 PLN, this will mean an increase of around 60 PLN. However, we must take into account the speculation about referendums in other countries – these may well lead to the same scenario being repeated, and to further rises.
Brexit and euro loans – better, but not entirely
Brexit proved rather neutral for the position of the euro against the main world currencies. Does that mean it did not affect Poles repaying mortgages denominated in euro? Not entirely.
As it turned out, the turmoil around Brexit not only strengthened the Swiss franc but also weakened the Polish currency. This in turn meant that, from the point of view of Poles, instalments paid in euro went up. In the days before the referendum the EUR/PLN rate hovered around 4.36-4.40; on the night before the results were announced it fell to 4.32, only to jump to 4.50 on the morning of 24 June. Later the euro rate fell slightly, reaching around 4.45 PLN.
For an instalment worth the equivalent of 2,000 PLN, this means costs that are 40 PLN higher.
READ ALSO – WHAT ARE THE CONSEQUENCES OF NOT REPAYING A MORTGAGE?
Brexit and a mortgage in PLN
For instalments paid in PLN no changes are visible so far, and people who, when investing in property, chose a loan in the currency in which they earn can feel safe.
How might Brexit affect PLN loans in the near future? If it turned out to weaken the economy, it is possible that the Monetary Policy Council would decide to cut interest rates to stimulate it. If it did not weaken it, the situation would not change much.
Tags: property financing, mortgages